Roof Replacement
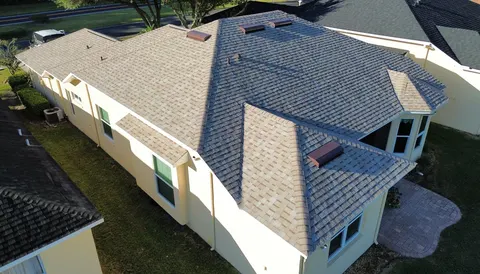
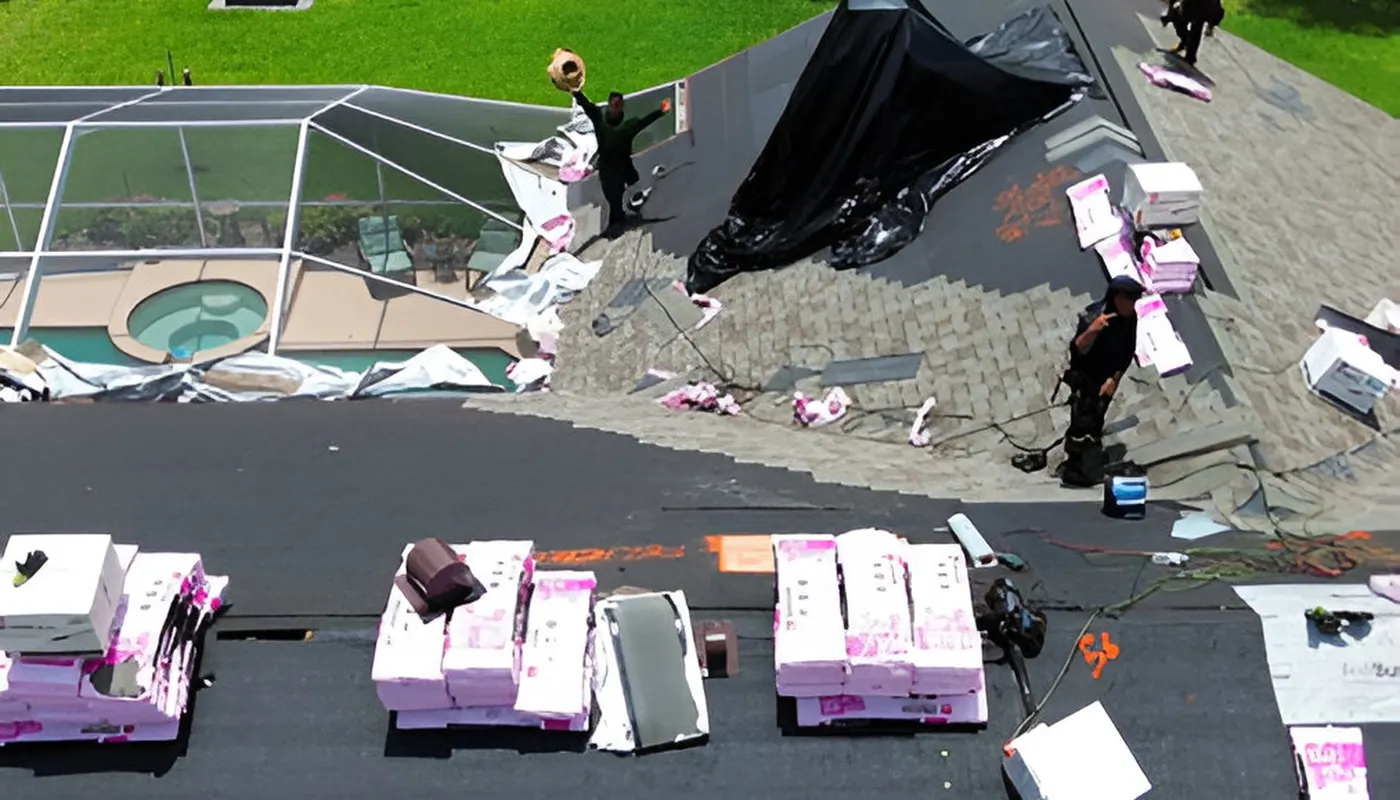
Full tear-off, decking inspected and repaired, then a complete system installed — usually one to two days on a typical Florida single-family home.
See detailsGuide
No. Under section 627.701(10)(a)5 of the Florida Statutes, a separate roof deductible may not be applied to a roof loss resulting from a hurricane. It also cannot be applied to a total loss under the valued policy law, to a roof loss from a tree or other hazard that punctures the roof deck, or to a loss requiring repair of less than 50 percent of the roof.
Step 1 of 2
Pricing your roof…
One momentThey will want to walk the roof: the drainage, the access and the deck are what price a flat system, and none of it shows up from the air.
One contract, one company responsible — JAC is a licensed general contractor as well as a roofer.
You are outside Tampa Bay and Central Florida, so this is a call rather than a price. Someone will tell you straight whether we can get to you.
If we cannot, we will say so and point you at someone who can. A roofer who drives two hours to a job is a roofer who is not there when it leaks.
A roofer from the Tampa Bay office will call you to book your free inspection. You get the same written roof report, photographed slope by slope, and a fixed price once someone has actually been on the roof.
We do not show an instant price on the Gulf Coast. The aerial pricing tool only covers Central Florida, and a number we cannot stand behind is worse than no number at all.
Nobody turns up unannounced. An estimator calls you at a time you agree to, with the price.
Since 2022, Florida insurers have been allowed to apply a deductible specific to roof losses, separate from your all-perils and hurricane deductibles. It is capped by statute at the lesser of 2 percent of your Coverage A dwelling limit or 50 percent of the cost to replace the roof.
Section 627.701(10)(a)5 lists them: a total loss to the primary structure caused by a covered peril under the valued policy law; a roof loss resulting from a hurricane as defined in section 627.4025(2)(c); a roof loss caused by a tree fall or other hazard that damages the roof and punctures the roof deck; and a roof loss requiring repair of less than 50 percent of the roof.
Where a roof deductible does legitimately apply to a loss, no other deductible may be applied to that same loss. You do not pay both.
Your insurer has to offer you a form, approved by the Office of Insurance Regulation, allowing you to decline the separate roof deductible. If you accept it, it must come with an actuarially sound premium credit. And if a carrier adds one at renewal, that requires a notice of change in policy terms and a right to decline.
This is the most commonly misapplied provision we see. After a hurricane, the roof deductible simply is not in play — your hurricane deductible is. If a carrier or an estimate applies a separate roof deductible to hurricane damage, that is worth questioning in writing, citing the section.
Need this doing rather than reading about? Storm Damage Restoration — Emergency tarping · free damage report.
This page is general information, not legal or insurance advice. Florida statutes and the Florida Building Code change; the citations here were checked in October 2026. For advice on your own policy or claim, speak to your agent, your carrier, or the Florida Department of Financial Services. JAC Builders does not interpret insurance policies — Florida law (s. 489.147) reserves that to licensed public adjusters.
It will be listed on your declarations page alongside the all-perils and hurricane deductibles. If you can't find it, ask your agent to confirm in writing.
No. The hurricane deductible is a percentage-based deductible that applies to all hurricane damage, typically triggered from when a hurricane watch or warning is issued. The roof deductible is a separate, roof-specific one — and it is the one that cannot apply to hurricane losses.
No, and you should walk away from anyone who offers. Section 489.147 makes it illegal for a contractor to offer any rebate, gift, cash, coupon or deductible waiver in exchange for a roof inspection or claim, with penalties up to $10,000 per violation.
Full tear-off, decking inspected and repaired, then a complete system installed — usually one to two days on a typical Florida single-family home.
See details
Pipe boots, lifted ridge cap, failed valley flashing, cracked tiles. We fix what is broken, and say so plainly when a repair is only buying months.
See details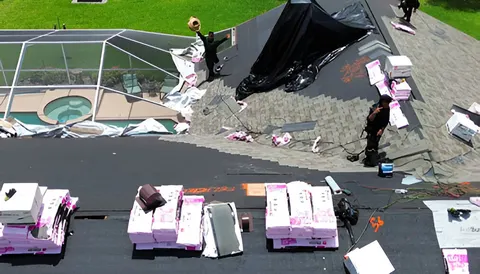
Tarp and dry-in first, then photograph the roof plane by plane and put it in writing — a report you can hand straight to your insurance carrier.
See details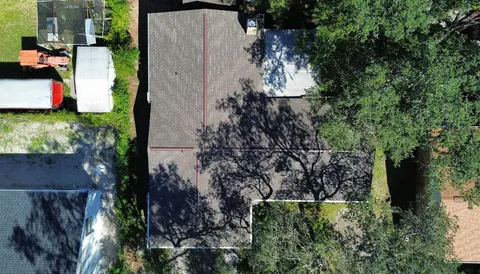
A written, photographed report on every slope, flashing and penetration, with the remaining life. Free, and yours to keep whether you hire us or not.
See details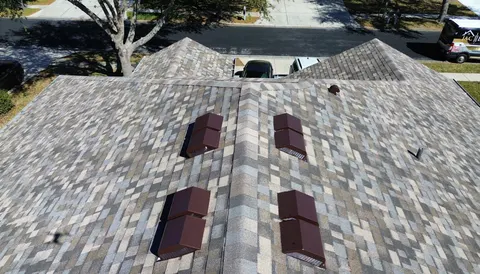
Architectural shingle installed as a complete system: underlayment, fastening pattern, metal and ventilation. Owens Corning Platinum Preferred.
See details
On tile the underlayment is the waterproofing, so most Florida tile work is re-underlayment: tiles off, a new system down, the same tiles back on.
See details
Standing seam and 5V crimp — 40 to 70 years, high wind ratings, and it sheds heat instead of holding it. Two to three times shingle up front.
See details
TPO, modified bitumen and flat systems, phased building by building so tenants keep trading and every unit is dried in before we leave each night.
See details
Gutters, soffit and fascia, re-roofing under an existing solar array, and the interior damage under a leak. We hold the general contractor's licence, so it is one contract, not two.
See detailsMon–Fri 8am–5pm · Sat 8am–12pm · storm and active-leak calls answered after hours. Call Tampa Bay on (813) 920-9644 — or send your address and we'll come and look at it.