Roof Replacement
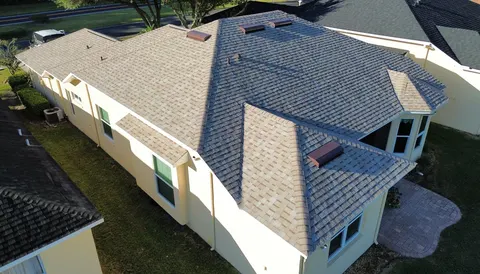
Full tear-off, decking inspected and repaired, then a complete system installed — usually one to two days on a typical Florida single-family home.
See detailsGuide
Updated October 2026 — includes the HB 815 / SB 808 correction.
Under Florida law passed in 2022 (SB 2-D), an insurer cannot refuse to write or renew a policy solely because a roof is less than 15 years old. For roofs 15 years or older, the homeowner has the right to get an inspection first — and if that inspection shows at least five years of remaining useful life, the insurer cannot refuse solely on the basis of roof age.
Step 1 of 2
Pricing your roof…
One momentThey will want to walk the roof: the drainage, the access and the deck are what price a flat system, and none of it shows up from the air.
One contract, one company responsible — JAC is a licensed general contractor as well as a roofer.
You are outside Tampa Bay and Central Florida, so this is a call rather than a price. Someone will tell you straight whether we can get to you.
If we cannot, we will say so and point you at someone who can. A roofer who drives two hours to a job is a roofer who is not there when it leaks.
A roofer from the Tampa Bay office will call you to book your free inspection. You get the same written roof report, photographed slope by slope, and a fixed price once someone has actually been on the roof.
We do not show an instant price on the Gulf Coast. The aerial pricing tool only covers Central Florida, and a number we cannot stand behind is worse than no number at all.
Nobody turns up unannounced. An estimator calls you at a time you agree to, with the price.
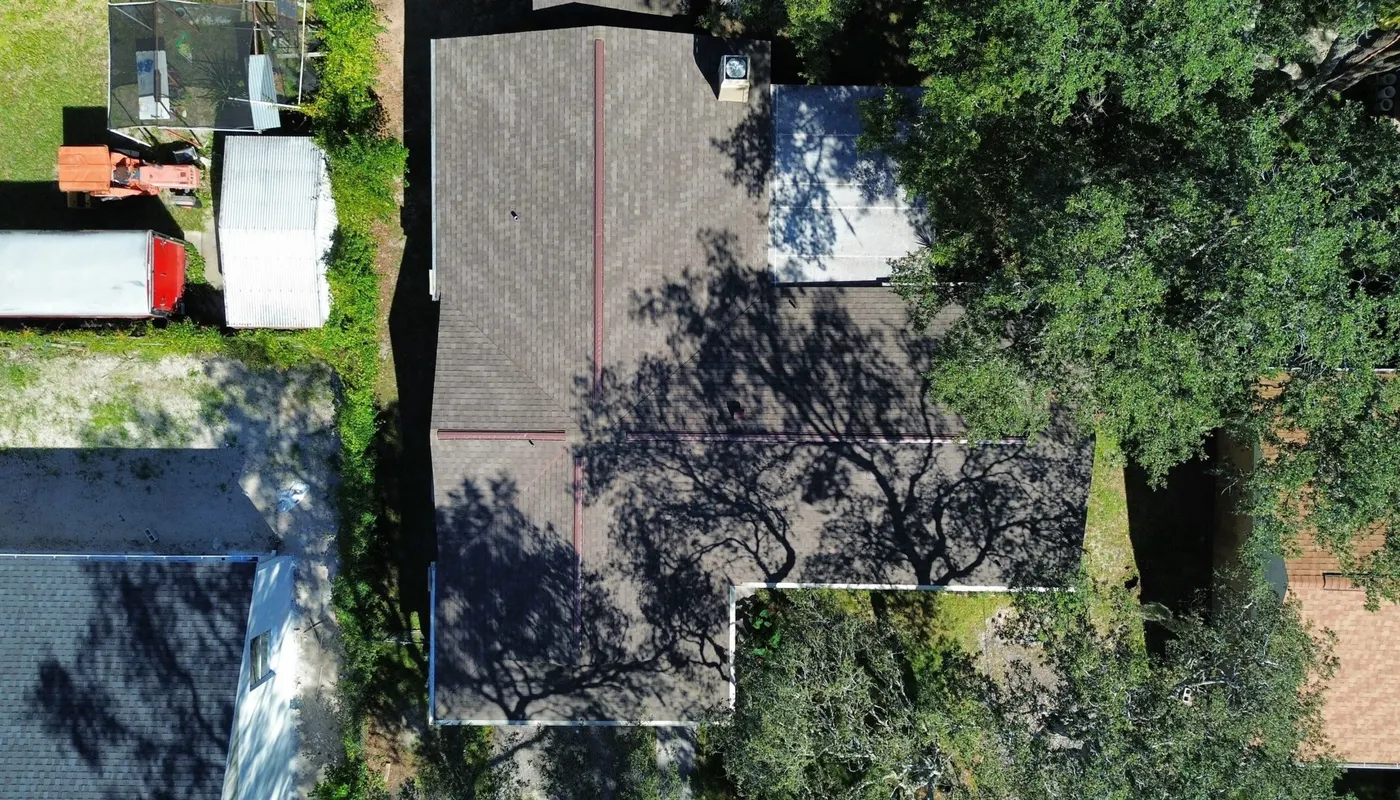
Before 2022, carriers were non-renewing sound roofs purely on age. SB 2-D set a floor: under 15 years, age alone is not a valid reason. At 15-plus, you are entitled to have an inspection done before a decision is made, and a documented five years of remaining life takes age off the table as the sole ground.
Condition, not just age — the state of the covering, fastening, flashings, and whether the system has meaningful remaining service life. A photographic roof report that documents each slope is what makes that case. A written note saying 'roof looks okay' will not.
Roof claims drove a large share of the losses that destabilised Florida's property insurance market, and underwriting tightened accordingly. Roof age is the single easiest variable for a carrier to price and it stays the first question on every application.
Read the deadline first, because it sets everything else. Then get an inspection with photographs. Three outcomes are possible: the roof documents well and you keep the policy, a repair resolves a specific cited defect, or replacement is genuinely the answer. The letter rarely tells you which.
Statute sets 15 years as the age at which an insurer may first require an inspection. Citizens Property Insurance goes further in its own underwriting rules: 'soft' roofs (shingle and similar) are capped at 25 years and 'hard' roofs (tile, slate, concrete, metal) at 50, after which you need an inspection documenting at least five years of remaining useful life — and a pass extends eligibility by five years at most. Read together: a Florida shingle roof is on notice at 15 and uninsurable-without-inspection at 25.
Citizens' rule is explicit that where a roof has been partially replaced, roof age is based on the oldest part of the roof. This is the single most expensive thing homeowners don't know: replacing one slope to save money can leave the policy priced off the twenty-year-old slope you left alone.
A great deal of contractor and agency content published in 2026 claims that HB 815 and SB 808 took effect on 1 July 2026 and extended roof-age protection. They did not. Both bills died in committee on 13 March 2026 — HB 815 in the House Insurance & Banking Subcommittee and SB 808 in Senate Banking and Insurance. Section 627.7011(5), as written in 2022, is still the operative law. If you've been told otherwise, check the bill history on flsenate.gov.
A separate wind mitigation inspection documents roof shape, deck attachment, roof-to-wall connection and secondary water barrier. Those credits attach to the windstorm portion of your premium and can be worth a substantial annual discount. A new roof built to current code usually scores far better than the one it replaced — see our guide to the new 2026 wind mitigation form.
Need this doing rather than reading about? Free Roof Inspection — Free · written report, you keep it.
This page is general information, not legal or insurance advice. Florida statutes and the Florida Building Code change; the citations here were checked in October 2026. For advice on your own policy or claim, speak to your agent, your carrier, or the Florida Department of Financial Services. JAC Builders does not interpret insurance policies — Florida law (s. 489.147) reserves that to licensed public adjusters.
There's no single statutory number. Practically, shingle roofs come under scrutiny around 15 years and tile and metal considerably later, since what the carrier is really asking about on a tile roof is the underlayment age.
Mid-term cancellation is restricted and generally requires specific grounds. Non-renewal at the end of the term is the far more common route, which is why the deadline on the letter matters.
Often meaningfully, through wind mitigation credits rather than through the roof's age by itself. Ask your agent to re-rate the policy once the new wind mitigation form is filed.
Full tear-off, decking inspected and repaired, then a complete system installed — usually one to two days on a typical Florida single-family home.
See details
Pipe boots, lifted ridge cap, failed valley flashing, cracked tiles. We fix what is broken, and say so plainly when a repair is only buying months.
See details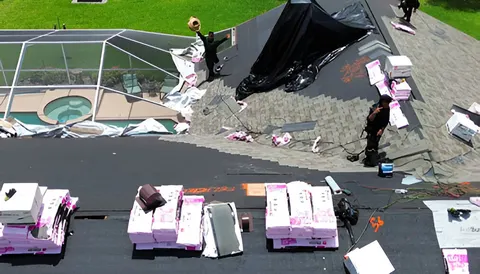
Tarp and dry-in first, then photograph the roof plane by plane and put it in writing — a report you can hand straight to your insurance carrier.
See details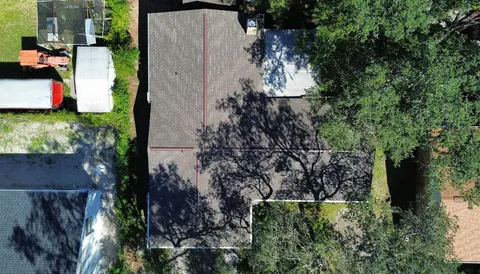
A written, photographed report on every slope, flashing and penetration, with the remaining life. Free, and yours to keep whether you hire us or not.
See details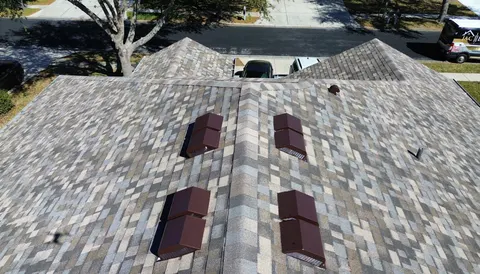
Architectural shingle installed as a complete system: underlayment, fastening pattern, metal and ventilation. Owens Corning Platinum Preferred.
See details
On tile the underlayment is the waterproofing, so most Florida tile work is re-underlayment: tiles off, a new system down, the same tiles back on.
See details
Standing seam and 5V crimp — 40 to 70 years, high wind ratings, and it sheds heat instead of holding it. Two to three times shingle up front.
See details
TPO, modified bitumen and flat systems, phased building by building so tenants keep trading and every unit is dried in before we leave each night.
See details
Gutters, soffit and fascia, re-roofing under an existing solar array, and the interior damage under a leak. We hold the general contractor's licence, so it is one contract, not two.
See detailsMon–Fri 8am–5pm · Sat 8am–12pm · storm and active-leak calls answered after hours. Call Tampa Bay on (813) 920-9644 — or send your address and we'll come and look at it.